Pricing and discount discipline for B2B manufacturers
Many manufacturers lose a meaningful share of margin through unstructured discounts, special terms and unprofitable accounts. Controlling them is often the fastest profit gain. Start by comparing list price with realised price by customer, product and salesperson, rank accounts by profit after freight, credit and service, then set discount bands with an approval path and review price realisation every month.
Steps
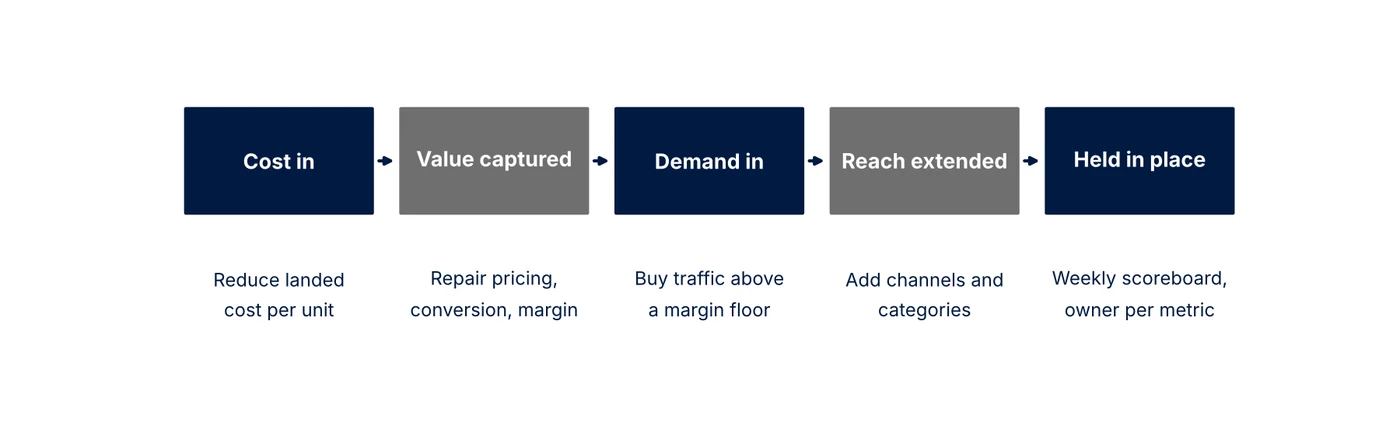
- Find the leak. Compare list price with realised price by customer, product and salesperson.
- Rank profitability by customer and SKU, including freight, credit and service costs.
- Set discount rules: limits by volume and customer type, with escalation for exceptions.
- Price on value for differentiated products, and use cost-plus only for commodities.
- Review terms: payment days, rebates, returns and freight conditions.
- Track monthly: price realisation, discount trend and margin by account.
Handling resistance
The sales team often fears losing orders. Show data on how many discounted deals were genuinely at risk, and pair the rules with coaching on value selling. When the team sees that discipline protects their targets as well as margin, adoption improves.
Customer conversations
For loss-making accounts, change terms, change scope or exit gradually. Do not abandon them suddenly. A conversation that starts from data about cost to serve is easier than one that starts from a demand.
Where the leak usually hides
The headline discount is rarely the problem. The leak is in everything around it: an extra cash discount for early payment that is taken even when payment is late, freight absorbed on small orders, free samples and tooling that are never invoiced, rebates paid on volumes that were not reached, and price increases that were announced but never applied to the largest accounts. None of these show up in a price list. All of them show up when realised price is reconciled against invoices and credit notes, line by line, for a full year.
Once the leak is visible, most of it can be recovered without losing a single customer. The rest becomes a deliberate choice rather than an accident.
Why this comes first
Recovering margin from the current order book is usually cheaper and faster than winning new orders. It also makes later growth spend more productive, because new customers join a business with sound economics. Read about GOP's Commercial Excellence & Value Capturing lever.
Common mistakes
- Giving the same discount to every large customer regardless of cost to serve.
- Letting salespeople approve their own exceptions.
- Ignoring payment terms, freight and returns when judging an account.
- Cutting prices to fill capacity without checking contribution margin.
A checklist you can use this week
- Pull twelve months of invoices and compare realised price with list price by customer.
- Rank the top twenty customers by profit after freight, credit and service.
- Draft discount bands by volume and customer type with an approval path.
- Review payment terms and returns for your five largest accounts.
- Set a monthly review of price realisation and discount trend.
Frequently asked questions
How much margin can discipline recover?
It varies by business and depends on how much unmanaged discounting exists today. A profitability review shows the size of the opportunity before any rule is changed.
Will we lose customers?
Some price-sensitive accounts may leave. A data-led review usually shows that the revenue at risk is smaller than feared, and that some of it was unprofitable anyway.
How do we price new products?
Start from value to the customer and cost to serve, test with a few accounts, and set discount limits from the beginning.
Related reading
Talk to GOP
Share where your business is today and where you want it to be. We will tell you honestly whether and how we can help.